Friday, May 22, 2009

REIT Maturities, Dig For Fire

Despite the whipsawing we're seeing CMBS spreads, there still hasn't been the "wave of mutilation" that everyone is expecting to see in the CRE space. But fear not, "stormy weather" is coming, and it's easy enough to "gouge away" at some of the obvious points - such as REIT loan maturities in '09 and '10.


We still have about $2.3 billion in REIT CMBS maturities over the rest of 2009, and $6.5 billion in 2010. Of the total from those two years, $6.5 billion is in the Conduit universe. The plot thickens past 2010, but this is a humble blog with no revenue other than ads (that no one clicks on). Please email credarkspace@gmail.com for further analysis and wiring details :).

There are actually some '06 vintage deals with heavy concentrations maturing in 2010 - these are 5-year loans originated in late '05. They include the Colonial Mall Glynn Place ($23mm - MLCFC 2006-1, CLP), Kenwood Town Center ($147mm - MLCFC 2006-1, GGP), and Alderwood Mall ($108.6mm - MSC 2006-T21, GGP).

Deals with heavy concentrations (>10%) of maturing REIT debt between now and end of 2010 include:

DEAL REIT Loans Mat. '09 & '10
WBCMT 2003-C8 25.5%
GMACC 2000-C3 23.1%
CCMSC 1999-C2 16.6%
MSDWC 2001-T1 13.0%
BSCMS 2000-WF2 12.9%
JPMCC 2005-LDP4 12.4%
WBCMT 2003-C9 11.6%
MLMT 2004-KEY2 10.6%
CSFB 2001-CK1 10.5%

On the one hand, you have original LTVs that are very low (between 55 and 68%), appreciation in all of these loans (even the shortest), high DSCR ratios, etc. and one would expect that these loans would have no problem refinancing in any market. On the other hand, you have the experience we just witnessed with GGP loans that also met all of those criteria. It seems the salient point in regards to the CMBS deals are the threat of extension, rather than actual losses, so you like IO and credit, and don't like short dupers on these deals.

The obvious other angle is to look at which REITs have the toughest mortgage maturity schedule. Some more work is required to fully analyze this, but a quick look and some challengeable (I might be making up a word here or there) data from Bloomberg, highlights a few names

REIT CMBS Maturing '09 and '10
GGP 2,252,552,611
DDR 548,001,132
Regency 387,626,486
SPG 374,168,033
CLP 340,774,373
Education Realty 285,103,248
Macerich 232,196,599
Extra Space 227,650,000
CBL & Assoc. 166,635,022
EPT 150,000,000
Equity Lifestyle 144,131,062
Host 135,000,000
Taubman 132,098,802
LaSalle Hotel 126,669,370
U-Store-It Trust 103,662,495


GGP is an obvious winner, but DDR has 21 properties with loans maturing over the next 18 months accounting for over 9% of their total debt outstanding, and nearly 20% of their CMBS debt outstanding. The next one in the list is Regency with $388mm maturing, over 18% of their total debt, and more than 40% of their outstanding CMBS.

Obviously there is much more to be done to really identify the right place to make a play here, but we'll post follow-ups. For what it is worth, I think the equity play is a little hard, because given what is priced into CMBS (despite the rally), equities are too rich, but all the names above are represented in the SRS ETF - probably better to short particular names though, if you're going the equity route. I think the plays are in the debt space. This is actually part 2 on Maturity Waves - see Part I, Wave of Mutiliation, published back in November 2008.

*I corrected the ticker to CLP for Colonial Properties Trust...

Thursday, May 21, 2009

Nothing to see here...

"Remember now, we’ve been talking about contagion for almost a year now and just have not seen it," said Mike Willoughby, chief credit officer of Regions Financial Corp. "We may have seen a couple of apartment projects come through, but nothing really to speak of. So, even though we start to look at what unemployment may do, we have not seen it come through our portfolio yet."

Hotel Tango CoStar

Tuesday, May 19, 2009

Macklowe - The Otera Catalyst


Macklowe is making a last ditch effort to save 1330 Ave of the Americas, which he effectively lost to Otera last month in the foreclosure auction. The play is to bring an equity partner and avoid the $12 mm in transfer tax costs. Macklowe and JV would pay Otera ~50% of their investment, the other mezz holders are already gone, and the taxpayer doesn't get the transfer tax (which seems grossly unfair, but that's another story). It's interesting how the foreclosure could actually end up benefiting Macklowe, even if he ends up a bit diluted given how much he put aside for renovations and whatnot.

Macklow has problems all over. He obviously overpaid for the EOP properties and lost GM and a number of other properties in that debacle, but he also has tenants fleeing (including 1330 AoA which has a 66.1% occupancy), and plummeting lease rates.

510 Madison was damaged by fire in February, and now two major tenants that were coming into the still-under-the-shovel building are trying to break their lease and recoup deposits. Tourneu had initially agreed to lease the ground floor retail space (3300 sq. ft.) and Jay Goldman & Co. had plans to lease the 19th floor of the 30 floor building.

TALF expanded to Legacy CMBS

Realpoint and DBRS were recognized as actual rating agencies in the same release - the world is really changing around us...

from Bloomberg:

Fed says legacy CMBS will become eligible for TALF The Federal Reserve Board announced that, starting in July, certain high-quality commercial mortgage-backed securities issued before January 1, 2009, or legacy CMBS, will become eligible collateral under the Term Asset-Backed Securities Loan Facility, or TALF. The TALF is designed to increase credit availability and support economic activity in part by facilitating renewed issuance of consumer and business asset-backed securities and CMBS. To be eligible as collateral for TALF loans, legacy CMBS must be senior in payment priority to all other interests in the underlying pool of commercial mortgages and, as detailed in the attached term sheet, meet certain other criteria designed to protect the Federal Reserve and the Treasury from credit risk. The FRBNY will review and reject as collateral any CMBS that does not meet the published terms or otherwise poses unacceptable risk.

CRE Losses at Banks

Everyone is waiting for this wave to hit, but the WSJ took a different look at it today and plugged the data from 900 or so regionals and locals into the "Stress Tests" previously performed on the 19 largest financial institutions.

The results were an expected $100 billion loss, and a possible $200 billion loss. That result is in line with some of the projections you see from other sources such as Goldman or Moody's, based on different kinds of analyses (Maturity schedules, credit quality, etc.). However, if you're like me and think the "Stress Test" were a joke, then you're also probably like me and think that Goldman and Moody's analyses were jokes as well. Nonetheless, an interesting take...

Total losses at those banks could surpass $200 billion over that period, according to the Journal's analysis, which utilized the same worst-case scenario the federal government used in its recent stress tests of 19 large banks. Under that scenario, more than 600 small and midsize banks could see their capital shrink to levels that usually are considered worrisome by federal regulators. The potential losses could exceed revenue over that period at nearly all the banks analyzed by the Journal.

Saturday, May 16, 2009

SEC Lawyers Accused of Insider Trading

I know this is soooo last week, but based on the reported facts, it sounds like it might just be an honest mistake on the two 'perps'. But, the lack of compliance within the SEC, and their rules in general stand in stark contrast to the rules your typical Investment Banker must adhere to...

SEC: One lawyer made 247 trades from 1/06 to 1/08, mostly in specific company names.

Contrast: Definitely no active trading - Buy and Hold is strongly encouraged.

SEC: Investment analytics tool: Google. Investment Results: 73% Decline in portfolio value.

Contrast: Investment decisions: Some Broker or third party analysis tool, company filings on Edgar, TGL/CreditSights/etc, everything you should've learned for your CFA, etc. Investment Results (for successful investors): mostly flat in recent years with single digit percentage point fluctuations. Investment Results (for the general market): 40% decline

SEC: No compliance officer. They had a reporting mechanism through human resources, but the post was not filled, and thus no one was there to report trades to.

Contrast: Many IBs require personnel to request special permission to trade ANY specific company name from their superior, and maintain restricted lists that must be closely adhered to. Failure to do so has dire consequences in addition to causing the bank to unwind the entire trade. Funds not considered diversified, are not even allowed without permission. There are even cases where the funds listed as options in 401(k) plans do not qualify as diversified under compliance-made-up rules and any trades are routinely unwound to the detriment of the employee. I personally regularly have received calls from compliance regarding investments (especially LP interests, LLCs, and individual trades - these all resulted in periodic calls with a compliance nimrod getting me to reaffirm it's purpose) during my employ at an IB - on the PUBLIC side.

SEC: 6 Month required hold periods on any stock purchases.

Contrast: 30 day holds. Although 6 months is a little too long in my opinion, knowing it was going to be at least 6 months before I could reevaluate my holding would have prevented me from entering virtually every equity trade I entered the last 10 years. The exception being some long-term coupon/dividend/royalty paying investments (mostly not stocks).

Friday, May 1, 2009

I've been liberated from my day job (working for "The Man") and I'm going to Disney World


Talf was extended to include 5 year terms, and some other CRE news surely happened today and likely will continue to happen in my absence. I highly recommend checking out M. Herschmeyer, Zero Hedge, Bodamer, and Deal Junkie for witty, thorough, and timely CRE comments until I get sucked back in and can no longer stand being liberated from the markets.

Dark Space may comment in my absence.

Return date is unknown. Final destination is unknown. There is no guarantee Freedom will last.

Thursday, April 30, 2009

Specially Serviced Loans Increase by 48% in 1Q; Defaults Increasing

Fitch notes that specially serviced loans increased 48% during 1Q '09, and 5 times as high as the end of 2007.

Heavy defaults this month are likely to make a lot of headlines.

Friday, April 24, 2009

We all make mistakes...

On this blog, there are various ads (which generate near-$0 because no one clicks them) and news links generated by google based on the content. So, I regularly click the news links because many times they are pertinent. Further, everyone makes mistakes, current author included, so I will not point them all out just to be mean, although the below is from the WSJ so I'll give $1 to whomever finds the most errors in this report:

US CMBS Deliquencies Up 18% In March; Only Health-Care Ppties Exempt

   DOW JONES NEWSWIRES

Standard & Poor's Ratings Services said the delinquency rate on U.S. commercial mortgage-backed securities, or CMBS, surged 28% just in March as the figure quickly approaches the peak following the last recession.

Commercial delinquencies, which long lagged the problems in the residential market, have been spiking since mid-2008 as the recession deepened, vacancies increased and new owners have been unable to refinance mortgages.

The rate climbed to 1.85% from 1.57% in February, putting the figure near the December 2003 peak of 1.96%. All property types, except health care, saw higher delinquency rates and delinquent amounts.

The office sector's delinquencies rate surged 48% just last month, while the amount of retail loans behind - $3.46 billion - overtook multifamily ones as the biggest source of delinquencies. A total of 98 retail loans became delinquent in March, with some related out-of-business chains like Circuit City and Linens 'n Things.

S&P said it continued to downgrade CMBS last month, cutting 130 ratings, while upgrading two. During the first quarter, 96% of 402 ratings actions were downgrades.

-By Kathy Shwiff, Dow Jones Newswires; 201-938-5975; Kathy.Shwiff@dowjones.com


I count 7.
  1. Deliquencies is not a word
  2. PPTIEs is not a word
  3. the delinquencies are either up 18% or 28% - which one?
  4. Delinquencies are not approaching the peak of the last recession. The 2001 recession had relatively low delinquencies (half today's levels), and the early 1990s had much higher delinquencies than 1.87%.
  5. Oh. She thinks there was a recession in 2003.
  6. A "surge" of 28 bps is not a surge (even the ironically named Glacial Surge represents an increase in velocity of a glacier up to 100 times it's normal speed)
  7. There were over 1500 CMBS rating actions in the first quarter.

Oh no she didnt... Highland bites back at Dillard's

Dillard's wanted to break it's lease that expires in 2017 because Highland Mall (JPMCC 2002-CIB4) is supposedly mismanaged and is now a ghost town, so they sue in court. Mind you the Dillard lease appears to have been renegotiated in 2007.

The mall is having issues: The 3Q 2008 numbers were 1.38x NCF DSCR and 81% occupancy down from prior year occupancies of 94+%, and significantly lower than the rest of the MSA. They lost JC Penney and apparently there is dark space (no relation) in that section of the mall. And there is a huge ongoing local dispute because the mall shut down early one day following a predominantly african-american track event - the NAACP has given speeches, names like Jim Crow were plastered on billboards, and a boycott has been sounded by african american and hispanic populations (this mall is in Texas) - so it has issues.

GGP and SPG jointly own the mall, so I guess Dillard's figured it could railroad its way around that pesky contractual lease given the problems at the parent co's. Nope. The mall counter sued Dillard's:

The mall’s owners ask for a declaratory judgment, attorneys’ fees and damages related to Dillard’s alleged breach of contract, “business disparagement” and “interference with business relations.”
Now their legal fees and judgments are likely to exceed any lease expense they could have had.

Searching for on-line law degrees with a focus on CRE law now...

Thursday, April 23, 2009

GGP - 164 Total Malls included in bankruptcy...

Still not sure how this will play out. Eight more malls added today.

Wednesday, April 22, 2009

Simon Preparing Jingle Mail?

Sounds like Simon might be preparing to turn in the keys on Palm Beach Mall. This is the 3rd largest loan, 5.8%, in JPMCC 2003-PM1A.

The property performance declined drastically last year (Madoff?) to just 0.63x DSCR for YE 2008 from 2007 DSCR of 1.32x. Simon has been covering the shortfall out of pocket, but apparently stopped doing so, according to Kris Hudson at the WSJ (sorry no link, but pasted below).

No special servicer notes were readily available. You'll recall that Eastland Mall (formerly Glimcher's) went through a similar process, but it dragged out for years and the saga continues today.


Pain in Palm Beach

Even the biggest landlords face losing properties to foreclosure in this recession. Take mall owner Simon Property Group Inc., which is poised to forfeit the 42-year-old Palm Beach Mall after the servicer on the mall's $51 million securitized mortgage initiated foreclosure proceedings last week.

Simon inherited the mall in West Palm Beach, Fla., when it bought two rival mall owners in 1996 and 1998. Even then, Palm Beach Mall was losing out to newer, ritzier malls in neighboring cities. Simon renovated it this decade, but it continued to decline and now is mostly empty. An effort to lure home-goods retailer Ikea was scuttled by the recession.

In recent years, all of the cash flow generated by Palm Beach Mall went to paying the interest on its mortgage. But it fell short in the past year, and Simon opted against chipping in extra money to cover the difference in March and this month.

Efforts to renegotiate the loan failed, according to a person familiar with the talks. A representative of the mortgage's servicer, Orix Capital Markets LLC, declined to comment, as did a Simon representative.

—Kris Hudson

Solana in WSJ: BACM 2007-1 and JPMCC 2007-LDPX

Solana was featured in the WSJ today regarding it's request for debt relief, which we commented on in early March, here.

Nothing much new. Noted that Travelocity did not renew it's 145k sq ft lease (they have a total of 540k sq ft), and that revenue was down 60% at the Marriott. Maguire is the guarantor, the person not the company, and has defended the request as just standard paper pushing - it is not standard when you call up the special servicer (unless you work at a distressed debt fund).

I really don't like Travelocity - you can't open your travel plans in different windows/tabs - it will just crash. They went to some effort to make it work in a non-userfriendly way, as evidenced by American Express travel, which uses Travelocity's framework for their website but just brands it as AmEx Travel. The American Express website doesn't have all the non-user-friendly bits. So, my point is that I'm negative on Solana.

Tuesday, April 21, 2009

Macklowe's 1330 AoA Seized

1330 Seized

Update:
The property is encumbered with a senior mortgage and mezzanine debt held by Otera (a unit of Caisse de dépôt et placement du Québec). So the term "auction" is used lightly - much like John Hancock tower earlier this month, there was likely one bidder and a distressed/non-market price, essentially held just to transfer control to the appropriate party. On the other hand, REFI implied nearly two months ago, that Otera had hired Eastdil to market the property for sale, so it's not 100% clear.

I do not know the auction results from yesterday - let me know ...

Update:
Control was transferred to Otera at least at a 1/4 discount to Macklowe's purchase price, but likely more...

Saturday, April 18, 2009

Tangle Up In Blue - CRE Investors wth Big Yachts


The 2008-C2 deal has since added another large delinquency to its list of problems. Regency Portfolio is a 60-day delinquent $25 mm loan on 20 properties mostly located in Iowa. The sponsor is a CRE firm run by two brothers (Rob and Jamie Myers) who actually come across as rather seasoned regional CRE investors and developers. They had multiple business offshoots, almost all in Iowa, that ran the gamut from shopping center development, to resi developments (largest home builder in Iowa). They got overleveraged, and spent too much time at the Resi trough, and just got caught up in the general hype that has crashed our dear market...

They've since had to layoff over 100 employees, defaulted on multiple loans, and been hauled in to court losing numerous assets in the fray.

They also owned a boat named the 63' yacht, RegenSea, which brings back memories of another CRE investor who defaulted on a slew of loans - Hurley Booth (Jr.), who owned a 41' footer down in Tallahassee named the ContingenSea. What cute boat names.

Hurley Booth missed some of the limelight when he defaulted on virtually all of his loans at once, because this all happened in late 2007 and early 2008 - right when the news was focused on MBS Companies (Michael B Smuck). Hurley owned a number of student housing complexes around Tallahassee and they are mostly REO now, although Midland has been a little slow to make that move on the loans it controls - not sure why. The loans were spread across three deals: FUNBC 2001-C4, JPMCC 2005-C13, and JPMCC 2006-C14. The Booth website has the tagline, "Building a Legacy" - surely they could've come up with something less ironic by now.

Do you know a CRE investor that owns a big yacht? Let us know and we'll see if they're behind on payments. ;-)

JPMCC 2008-C2 & JPMCC 2007-C1 Appraisal Reductions


The fact that there were appraisal reductions related to the Promenade Shops at Dos Lagos and the Westin Portfolio (in both JPMCC 2007-C1 and 2008-C2), which were so widely reported in November they helped move the market to historical wides, was no surprise. However, the ASER calculation was off by a $100,000 on the Promenade Shops loan - a mistake that you really don't expect to see. It is a rather simple calculation.

Keeping in mind the '08 deal in particular was a small deal dominated by several large weak loans, the interest shortfall reached high into the capital stack effecting as high up as the A-rated (orig. rating) F class (higher if they stick to the incorrect calculation - there has not been a comment on the error yet...). This is significant - the subordination rate on this class is over 9% (3x historical losses) and it's already being hit with shortfalls. Again, it was a weak deal, a small deal, and a chunky deal, but a significant event nonetheless.

The 2008-C2 deal has since added another large delinquency to its list of problems. Regency Portfolio is a 60-day delinquent $25 mm loan on 20 properties mostly located in Iowa. More on this later...

The whole story is worth putting up the picture of the man, J.P. Morgan, with a knife in his hand ready to cut out the entrails of the poor originator who made these pathetic loans in the first place.

DDR Portfolio For Sale

DDR has a small portfolio for sale...


Disposition and Gain Activities

During the first quarter, the Company completed $48.4 million in aggregate of dispositions at an average cap rate of 7.4%. Subsequent to quarter end an additional asset closed for $15 million.

The Company currently has assets in its operating portfolio that are under contract for sale for an aggregate sales price of approximately $32 million, as well as approximately $72 million that are currently under non-binding letters of intent scheduled for completion in 2009, subject to certain conditions. Additionally, the Company has $300 million of properties already in the market with brokers and anticipates taking an additional $290 million to market within the next month.

Johnny Hendrix, Executive Vice President and Asset Management said, "We are making good headway in our desire to achieve our full year dispositions goal, however, we provide no assurance that we will be successful in closing these transactions."


CMBS Loans Harder To Negotiate Because More Parties Involved?

I repeatedly hear how CMBS loans are more problematic because there are so many parties involved in each loan. It came up again this week with the GGP bankruptcy.

Let's be crystal clear here. You default on a loan, you have 1 party to deal with, and it is the Special Servicer. That is their precise job, and they get paid 100 bps for doing it. You do not deal with the master servicer, bond holders, originator, trustee, or anyone else.

The Special has some pretty defined steps they may take in order to resolve the loan. They can foreclose on it, put in place new management, and eventually sell the property and apply any recoveries to the Trust (after taking out for any expenses involved). Alternatively, they can extend the loan term, generally for 1 year at a time, and rarely more than 2 years. Without any data to back it up, but with reasonable insight, these two options account for the overwhelming majority of workouts on defaulted loans.

It is not supposed to be easy to violate a contract you signed on a mortgage document - so, you don't get to complain about it too much.

Friday, April 17, 2009

CRE Developments

Obviously there have been some news this week, and I've been unfocused on the markets with little time to comment or share thoughts.

GGP filing is the big one, despite the fact that it has been widely anticipated for quite some time and is still trading above it's lows set pre-bankruptcy. It was a little surprising to see a fair amount of the bankruptcy remote SPEs that own the malls run by GGP included in the bankruptcy filing, but I think some folks' conclusions are a little too early and may prove to be wrong. At the end of the day, even though it is a bunch of malls, their CMBS is low-levered and has great cash flow.

That being noted, I spent a fair amount of time while traveling this week reading other blogs while squinting at a PDA and waiting on some form of transit. I'm a strong supporter of many well written blogs, and generally believe they provide a better source of information than the legacy news organizations. You cannot even compare the innacurate and insufficient 'news' from sources such as Johnathan Weil's columns in Bloomberg to a well-argued and fact-supported blog entry from the likes of Zero Hedge or Calculated Risk. Even some linkfest format blogs are well thought-out, and can be useful. However, occasionally you catch the blogs that you really like stepping outside the bounds of their knowledge and jumping on the journalistic hysteria bandwagon, and it's just ashame (sorry no links, but the initials are ZH and CR).

But I digress, some other stuff happened this week too. Vacancies increased, Beige Book was released and was negative, The Donald saying things like you'd have to be dumb not to be buying CRE (I actually saw this during the 5 minutes I was in front of a TV), and DDR put up a portfolio of 52 shopping centers up for sale.

The DDR was the most interesting, and mostly overlooked, bit in my opinion. A number of the loans are in outstanding CMBS deals from 2003ish, and more are in late 1990s transactions that have since paid down or defeased. Most are in the NE (so none of these are in the big SE portfolio that you're thinking of in CGCMT 2007-C6 - which has seen the AMs traded a fair amount in the 1Q 2009). Some of the properties are likely to be even more desirable to buyers because they can assume the loans with very generous underwriting relative to any loan they'd be able to get today. That's probably the only thing DDR has going for it - you're not really supposed to sell in the trough part of the cycle...

Tuesday, April 14, 2009

GGP Sued Over March 16th Maturity

From the WSJ:
Law firm Wilmer Cutler Pickering Hale and Dorr LLP on Monday sent a letter to General Growth and one of its outside law firms explaining that it represents holders of 25% of the company's $395 million in bonds due last March 16 that weren't paid, according to people familiar with the matter. Bondholders must collectively represent at least 25% of a given bond issue to compel a trustee to act on their behalf.

The GGP situation continues to be interesting. The malls are cashflowing and low-leveraged for the most part, while the company is highly levered and is swamped with maturities that it can't refi because there is no market to refi into. I continue to believe that there are recent investors (maybe Ackman) who have bought the longer-dated corporate debt for pennies, only to force a bankruptcy where they are likely to get paid back near par.

GGP Maturity Default - Jordan Creek


This is last week's news, but GGP had another loan pass its maturity date - $165 mm Jordan Creek. 3Q 2008 NCF DSCR - 1.72x, 95% occupancy.

Saturday, April 11, 2009

Weekend Reading

FDIC Publishes Public Comments Regarding PPIP - good for a little chuckle...

Hotel Tango Zero Hedge

Tuesday, April 7, 2009

S&P Places 2,648 classes on Watch - Over 100 are AAAs

S&P placed over 100 CMBS AAAs including 20% super seniors, AJs, and IOs on Rating Watch Negative this morning.

Again, this is not unexpected and is in fact an extremely delayed reaction on their part. The 20% super seniors (these are prior to the 30% super dupers - I hate that word) are a bit of a surprise, but not really. I expect this will reign in some of the tightening temporarily, but look for spreads to continue their momentum tighter until some truly bad news regarding CRE starts rolling in.

These little tidbits about 15% price declines, John Hancock, and 1.8% delinquency rates aren't really *bad enough* to drive prices lower than the already distressed prices in the market. Frankly, PPIP et. al. are not good enough to whip prices higher at a faster pace either.

Monday, April 6, 2009

S&P Prepping For Wave of Downgrades - Surf's Up!

S&P says recent US CMBS highly susceptible to cuts

Mon Apr 6, 2009 3:22pm EDT

NEW YORK, April 6 (Reuters) - Standard & Poor's on Monday said it will make negative pronouncements on U.S. commercial mortgage-backed securities on a "large scale" in coming days after a review of the securities.

The most-recently issued CMBS are "highly susceptible" to downgrades, including top-rated "AAA" issues, after the review that accounted for eroding real estate markets, lack of financing for the assets, and the economic recession.

Friday, April 3, 2009

Who is making and receiving mortgages -- Bank of Amerillwide

The fine researchers at Bank of Amerillwide put out a good list of loans and extensions, some of which were news to us. See below:

Macerich - Refied two mortgages, extended two. Shops at North Bridge received a $205 mm 7-year, 7.5% coupon mortgage from insurance money; it refies a $205 mm pari passu loan with a 4.67% coupon in LBUBS 2004-C6 and MSC 2004-IQ8, but the new DSCR is still roughly 1.89x using 3Q 08 annualized net cash flow numbers. On a separate unamed property, they closed a $115 million bank loan with a 2-year term floater at L+350 bps with a 5.25% floor.

Macerich also extend the $54 mm Inland Center in San Bernadino (LBUBS 2004-C2) loan all the way out to 2/2011 with a 50 bp coupon step-up every 6 months. BOMLW points out that this destroys the A2 holder who would have been paid down substantially had the loan paid off as scheduled. Again, the other extended loan remains unamed but received a 2-year extension as well.

The mention the two Simon malls in LBCMT 1999-C1 that we discussed yesterday.

Brandywine closed a $90 mm mortgage on a Philly office building taking out a soon to be maturing loan of $69mm. No further details.

Liberty also reported 6 separate loans funded by life insurance for a total of $317 mm. Half floaters and half fixed, with an all-in coupon of 7.1%.

Thursday, April 2, 2009

Link Fest

JER delisted due to CMBS.

UK distressed debt funds lining up.

Stocks are up on no real news, and spreads are down on the same.

Office Vacancies15.2%


Office Vacancies are up 70 bps to 15.2% according to the REIS' data.

It's going to get much worse than that. I expect it to exceed 20% by year-end.

Don't read the WSJ article about this, btw, LingLing muddles fact and fiction. The headline is accurate though, and their graph is very nice (see right).

LBCMT 1999-C1 - Two Simon Loans Refi

The two large Simon sponsored loans in this deal matured in the first quarter of this year, and apparently refied without any problems. Both loans were purportedly done through insurance company money, allowed Simon to take out new 10-year loans with interest rates just 70-75 bps higher than the old loans. Further, the loans were originated in 1999, so they had 10-years of embedded appreciation, so Simon was able to take out significant equity on the two loans.

LBCMT 1999-C1 New Loan
Penn Square Mall
Rate 7.025% 7.75%
Orig. Bal. $74.8mm $100mm
Most Recent $65.8mm

Woodland Hills
Rate 7.00% 7.79%
Orig. Bal. $89.6mm $97.5 mm
Most Recent $78.6mm

Both of the prior loans were amortizing, so Simon took out a signficant $53.1 mm in cash out of the deal. This is realy what I expect to see in the coming "wave of maturities" - the exception being the 5-year loans starting in earnest in late 2010 and 2011 that seem problematic to me.

2008 YE for Penn Square was a 3.34x DSCR - why doesn't anyone report that! I stumbled across these refis (Hotel Tango Journal Record), but had no problem finding the maturity default last week on another of their malls


Mark-to-Market - No Change of Opinion

I was absolutely floored by the activity generated by the mark-to-market changes today, so I went back and re-read the proposals. I'm not getting it - there really isn't any significant change in the proposals. Really, there isn't.

Now someone will come back and say that everyone else is saying that it's going to allow the evil banks to mark their positions to some fantasy level - but, they already are. You can't mark these things up any higher than 100%!

This ultimately changes nothing. The relatively insignificant changes it makes to where you can bucket your loss is just another thing you need to analyze (discount) before you invest in the company in question.

The market is dying for good news...

John Hancock Tower

John Hancock Tower has received ample coverage elsewhere, but it deserves a little clarification. At the risk of sounding like an optimist (please don't accuse me of that), it really doesn't imply much at all for commercial real estate in general.

Some believe it implies severe price corrections are coming for CMBS, but it doesn't really tell that story. The sole bidder had been buying up the mezz position for months - not only did they have a higher basis, but who would bid against them? They obviously are going to protect their position, so no serious bidder is going to compete, thus guaranteeing a low price.
Others point to it and say it proves CMBS are a good investment because the senior mortgage isn't close to taking a hit on this one. That is not fair either. The average LTV is just below 70% in CMBS, significantly higher than the 50 handle LTV on this loan. Further, LTV has historically been somewhat correlated to credit (lower credit requires a lower LTV by the underwriter), but that wasn't the case in recent years where lower credits could come into CMBS and receive high senior LTVs (some of the lowest LTVs went to high credit institutional investors).

Monday, March 30, 2009

The Source Maturity Default

The Source matured 2 weeks ago with no payoff...

This particular mall has been hit with multiple bad exposures - Steve & Barry's, Circuit City (3rd largest tenant), and Fortunoff. I prefer to wait on the sidelines to see how this one plays out. I haven't looked at the financials to see how much those tenants contributed to the bottom line, but the mall was performing well last year, it has 10 years of appreciation built into it, and it might be a likely extension (again, not knowing the details).

It should be widely reported today - it's already here and here. This is the sort of news the CMBS sector needs to nip last week's rally in the bud - we can't have strong rally's, we're in a recession folks. Save your money for ammo and water.

Tuesday, March 24, 2009

Toxic Asset Marks?

If Goldman is right (not necessarily the case), the average carrying value for banks on Comm. Mortgages is just 95%. Surprisingly, C&I loans is even HIGHER at 96%. BAC, for example, is carrying Comm. Mortgages at 100%!, so is Citi!

Hotel Tango ZeroHedge.blogspot.com - go check out his site for the chart

PPIP, REIT maturities, Retail Severities, Premier Properties

Goldman talks their CRE book (hopefully, otherwise their conclusions are insane).

->I'll post a more useful analysis on REIT maturities here in the next couple of weeks.

S&P adjusts retail outlook, but still not negative enough. Looking for 44% loss severities. Also noted ICSC is predicting 73,000 stores will close 1H ’09.

Chris P White's Premier Properties was in the news again yesterday.

Obviously, the big news is the Treasury's plan to buy 'toxic assets'. My initial digest of it was that it would fix all the problems, but on further reflection, it's less powerful than it seems for CMBS. It should still lead to sustained, but measured, tightening, however, it only includes currently-rated AAAs for CMBS, which excludes nearly every AJ (as soon as S&P/Fitch start their downgrades). It could be a boon for New Issue by helping to clean the overhand on IB's loan conduits that never got securitized, and might lead to some large loan deals. I still don't have the details on whether positions will be marked daily and margin-called, how much it will cost and investor, and whether or not there will be term-matching. Not to mention whether the evil investors will be burned at the stake if they profit from this program.

Friday, March 20, 2009

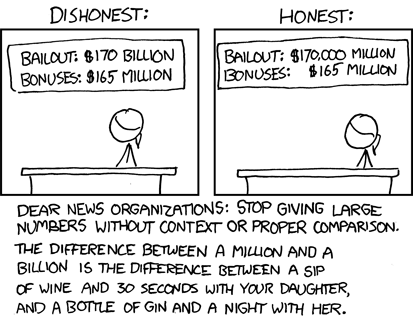
Difference Between a Million and a Billion


Hotel Tango: Barry Ritholtz and Bradman

SPG 10.875% 2018 sells $650mm

The debt was heavily oversubscribed and upsized from $500mm. It traded at a discount to their 2019 notes by over 100 bps, and was very rich to A CMBS with over 5,000 bps of spread between the two. The new issue matures in 2018.

GGP Defaults on CMBS loans

Again, others follow GGP more closely than I, but it would be remiss of me not to send you today's headline story. GGP had a maturity default (or near-maturity in 1 case) on three (3) CMBS loans in two different deals, S&P & Moody's quickly downgraded the company to C, multiple executives were changed out, and they face a 5pm (today) deadline on debt unrelated to the CMBS deals.

The kicker on the CMBS deals, is that the malls are performing wonderfully (even though they ARE malls). Here are the numbers:

LBUBS 2004-C4
  • Town East Mall
  • $105mm outstanding sr. mtg.
  • Matures 4/11/09
  • 3Q 08 NCF DSCR 2.45 and Occupany at 99%
  • 3 Major Tenants: Sears, Dillard's, JCP
  • Next Pay Bond: A2 - $185mm outstanding. Likely to extend in foreclosure.
GCCFC 2004-GG1
  • Southland Mall
  • $81.3 outstanding
  • Matured 3/1/09
  • 3Q 08 NCF DSCR 2.69 and Occupany at 98%
  • 3 Major Tenants: Sears, Macy's, JCP

  • Deerbrook Mall
  • $73.8 outstanding
  • Matured 3/1/09
  • 3Q 08 NCF DSCR 2.55 and Occupany at 99%
  • 3 Major Tenants: Dillard's, Sears, Macy's
  • Next Pay Bond: A3 - $54mm outstanding. Likely to extend in foreclosure.
  • Remaining partially pays down A4 - $296mm outstanding

These two deals are likely to face extensions, and there might be some plays around timing that extension - the near-pay bonds are all trading with high-teen yields; and the b-pieces are likely trading for next to nothing. The more interesting CMBS trade would be to pick up near-pays on other CMBS deals with GGP exposure; these would pay off early if GGP has to sell assets. People have already piled in on this trade, though, so you'd be arriving fashionably late.

GGP's maturing CMBS debt by year:

Mat. Year Curr. Balance Num. Loans
2009 1,540,257,761 16
2010 3,780,728,494 37
2011 5,233,299,013 39
2012 1,521,498,883 16
2013 1,001,499,652 15


Thursday, March 19, 2009

Mark to Market Changes

I'm very interested in other folks' opinions on these, but I do not see the level of changes required to make the market snap back for CMBS. They use a CDO in one of the examples, and that may be a different story, but nothing I see in the proposed revisions help CMBS without some less-than-truthful presumptions made by the reporting entities.

At the risk of making our readers dumberer, Jonathan Weil, of Bloomberg, believes the proposed changes will create an STD-ridden cathouse (his analogy) out of the market, but most of the points he highlights are not changes - they're part of the current rules. His example hiding losses on stock holdings of AIG (Average Daily Volume: 80+ million shares) and Fannie Mae (Average Daily Volume: 20 million shares) fails both tests in both the current and proposed set of rules, and companies would still have to report these losses as usual.

Mr. Weil also notes that two members of the panel "opposed" the changes. In reality, the "opposing" proposal was also included in the FSP as an alternative view. They actually agree with the FSP 157-e in regards to determing whether or not a market is active and a transaction is distressed. The big difference in their argument is that A) FASB should work with IASB and come up with a joint agreement to avoid accounting arbitrage, and B) Other-than-temporary impairements should be reflected as an unrealized loss to earnings.

Outside of the journalistic bubble, market particpants realize that FASB's fair value accounting standards are obviously broken (and were broken when they were created). The current environment has highlighted the problem. I don't think it's fair to say FAS 157 created the current problems, but it is contributing to them. I'm biased towards CMBS, so its easy to walk over to the loan trading desk and look at a pool of senior mortgages trading at 80 cents on the dollar, and then walk over to the CMBS desk and see a pool of mortgages with a CUSIP attached (but otherwise identical) trading at sub 50 cents... well, something is wrong there. The 80 cent pool is being priced with some credit concern factored in, and the CUSIP'd pool is factoring credit concerns, but is mostly factoring in liquidity concerns. If you plan to hold both until they mature in 8 years, why should you price them differently?

He probably isn't a fan of "Secret Diary of a Call Girl" either


CRE Prices down another 5.5%


January's decline was the largest since Moody's CPPI index started in 2000.
Prices are now down 19.1% from a year ago and 15.4% lower than they were two years ago. They have declined 21.0% from their peak in October 2007. Prices have nominally returned to the levels they were in the spring of 2005, says Moody's.


Complexity

Another MBA story, this one regarding complexities surrounding CMBS. I was interested, hoping to gain another's insight into special servicing conflicts, or pari passu workouts. It's leaves a lot to be desired.
"they believed in the bond they were offering as well," but it turned into "slices of slices of slices," Fasulo said.
Is he talking about CMBS anymore? He must be talking about some CDO of CMBS, but is just misquoted here. But then, the next quote...

"[Bondholders] have lost track of their investments because there are so many iterations of slicing and dicing," Korologos said. "It's hard to put a finger on what [they] really have. That's how complex it's become."
... is equally confusing.

There's also a half sentence regarding loans maturing 6+ years down the road that seems a little half-baked and premature
loans maturing in 2015, depending on leverage, property markets values, liquidity and appetite for 75 percent to 85 percent leverage at the time of maturity, could face challenges in addition to loans maturing in the near future.
I'd recommend skipping the article, but you just know its going to be on CNBC, or worse, Dateline "How to Catch a Trader" segment with the quote, "These CMBS securities were all sliced and diced to create AAAs, and are just as bad as Subprime". These guys have good pedigrees too.

Commercial Mortgage Market Grew last year?!

The Mortgage Banker's Association noted today that Commercial Mortgages INCREASED last year by 5%, or $166 Billion.

Also noted that CMBS made up just 13% of the outstanding mortgages, but more surprising to me is that Insurance Co. share dropped by 11% - I had assumed they were taking market share from the void created by CMBS. The commercial banks (up 11%) and specialty finance companies (up 23%) are both taking significant market share, and of course the GSEs (up 23%) are responsible for virtually all of the MF lending.

Wednesday, March 18, 2009

Cap Rates

CoStar has an article out with some cap rate numbers based on the Korpacz Real Estate Investor Survey:


Class A Office:
4Q 07: 6.1%; 180 transactions
3Q 08: 6.6%;
4Q 08: 7.6%; 80 transactions
1Q 09: 7.9%; (thru 3/18); 42 transactions

Warehouse & Distribution:
4Q 07: 7.1%; 279 transactions
4Q 08: 8.1%;
1Q 09: 8.6%;

Multifamily
4Q 07: 5.9%; 629 transactions
4Q 08: 6.8%; 355 transactions
1Q 09; 6.8%


Mark-to-market FSPs released today

FSPs are the "FASB Staff Position" on proposals. They have some initial guidance and proposals, and allow for feedback from the market.

Here's the one on FAS 157-e and here is the one on the related 115-e, 124-e and EITF 99-20b.

I'm not sure if CMBS makes the cut based on the factors their using to determine a non-existent market place (in FAS 157-e). CMBS are actively traded, and bid-ask spreads aren't really that wide (their pretty narrow at the AAA level) relatively speaking. Although you can get widely disperse pricing on comparable bonds from EJV or whatever pricing service you use, you get close to the same answer if you go to Barcleh or BancOfAmerillwide - and they price the entire market every day for their indices. The only factor that CMBS seems to qualify for is the "Abnormal liquidity risk premiums... blah blah ... compared to reasonable estimates".

The other docs really don't seem to effect CMBS differently than they have in the past. They both note that if management does not anticipate selling the security before recovery, and using reasonable estimates... type of language. I need to read through them in more detail, and I'll post an update if I get any more out of it.

GGP Reprieve Redux

I can't compete with David Bodamer's timely and accurate tracking of GGP - go check his latest update and historical news updates here.

Ackman didn't force default, but I still wonder if, at the end of the day, we all realize that there was some vulture player who picked up the debt real cheap, maybe it's debt that doesn't even mature for some time, and he forces their hand to get paid back early in the bankruptcy process.

The vast majority of GGP malls are performing great, spectacular even. That will not last as more of the retail bankruptcies play out, but I think the debt holders are unlikely to take much of a hit even in a fire sale situation.

Solana Seeks Debt Relief

Solana is a huge multi-use complex in Westlake, TX owned by Robert Maguire (the man, not the company). It was doing fine last year, but something obviously has gone wrong - its not clear what yet. However, we've never been a fan of Maguire's business model with so much exposure to California, and a surprisingly high amount of exposure to mortgage origination and servicer operations, and even more surprisingly high exposure to the subprime variety!

Solana is has pari passu mortgages in BACM 2007-1 and JPMCC 2007-LDPX.

Fitch:


Solana is secured by a 1.9 million square foot (sf) mixed-use property located in Westlake, TX. The property contains office, retail, and hotel components. The loan transferred to special servicing when the sponsor requested payment relief. As of June 2008, the servicer reported a debt service coverage ratio of 1.88 times (x) and occupancy of 98%.

Tuesday, March 17, 2009

Hyatt Regency Boston Trades for $220k per Key

CoStar reports the Hyatt purchased the hotel for $110 mm from Host.

Hyatt Corp. has purchased the Hyatt Regency in downtown Boston from Host Hotels & Resorts for $110 million, or more than $220,000 per room, CoStar has confirmed.

The 22-story hotel has 498 rooms at 1 Avenue De Lafayette, a few blocks east of Boston Common. It was constructed in 1984 and renovated in 2001, and earned the government's Energy Star label in December for its energy efficiency. It includes a business center, fitness center, indoor pool and a spa, and a steam room and sauna.

Please see CoStar COMPS #1663405 for additional information.

Monday, March 16, 2009

CMBS Linkfest

GGP, GGP - it's debt is maturing. Next Story.

I'm a vulture fund manager - what's distressed debt?

I'm a CEO, what is power?

I'm an Insurance Company/Bank/Financial Services Firm, what is Mark-to-Market ?

I'm FASB, really, what is mark-to-market?

I'm a banker, what is a redneck?

I'm the French President, did my wife just say something about a turd in her pants?

Is she also a super model?

Ok, Mr. President wins.

Friday, March 13, 2009

Mark to Market Changes - April Business

In the CMBS world, we have very tangible examples of how Mark-to-Market rules (FAS 157) are putting undue pressure on the market. It is easy to point to a CMBS deal with a single asset trading at 60 cents on the dollar, while a non-cusip loan with essentially the same collateral trades at 98 cents on the dollar. Obviously there is something wrong with that valuation. You'll find folks have very strong opinions on both sides of the issue, and I will not argue its fallibility or utility, except to state the obvious - it doesn't work in its current form.

Robert Hertz, the FASB Chairman, indicated yesterday in front of Rep. Kanjorski (and the rest of the Subcommittee on Capital Markets, Insurance, and Government Sponsored Enterprises) that there would be significant changes within the next 3 weeks.

The same folks that have strong opinions regarding the FAS 157 rule, also have strong opinions about the impact of any changes. Numbers are quoted, arguments are made regarding the relatively small portion of held-for-sale assets that are affected, etc., etc. It is a broad issue, no matter what numbers you're looking at. Any change could substantially move markets.

Full disclosure: I try to be somewhat non-biased about things, but I think FASB is full of idiots.

Tuesday, March 10, 2009

Mark to Market, Mark the Date March 12th


A suspension of Mark-to-Market accounting would whipsaw spreads in dramatically across all markets, but it would be most noticeable in CMBS. The discount in CMBS is much more a liquidity event, rather than a credit/fear event. If they suspend it altogether, it means a huge rally across the board - equities, corporates, MBS, etc.

The house is going to have a talk about it on Thursday.

Remit Day


Today we wait. We wait for the analysts to suck in all of the data from the 60%+ of the deals in the US CMBS universe that pay on the 10th so we can stare at it. We'll probably get our first glance late this week, although any new big delinquencies might start making the WSJ before then if they are interesting enough. Since I don't have it yet, let's just pick the absolute worst numbers from last month's remits.

Worst Total Delinquency Rate (including 30+ through REO) by State, Property Type, and Deal Type:
Nevada - 3.33%
Senior Housing - 2.99% (followed closely by multifamily @ 2.67%)
Credit Tenant Lease deals - 3.91%

Sunday, March 8, 2009

PCV/ST loses another case - $200 million on the line


Deal Junkie brought our attention to the fact that PCV/ST just lost a case in appellate court that could cost them $200 million that would go to roughly 3,000 tenants who received illegal rent increases.

The case revolves around the fact that PCV/ST received a tax break through the J-51 tax program, which allows breaks for renovations on rent-regulated apartments and encourages capital improvements by tenants as well. The NYTimes implies that the outlook is bleak for the owners.

Tuesday, March 3, 2009

We're Halfway There!

Some very long-term landmarks are in sight. Right below Dow 7000, not 2% down from here, is a point at which half of the entire rise from the 1932 Depression low to the ultimate October 2007 high will have gone away. That's explainable given the low-double-digit Dow of '32, but losing half of 75 years worth of upside in 16 months is . . . quite something.


-Barron's Mike Santoli

Monday, March 2, 2009

Extended Stay

Extended Stay started creeping back into the news...

It has never been clear how this loan was expected to survive, even at origination. I previously went into it at length, here and here.


Image from Hans Van DeVorst (.com)

Zoning Laws need Flexibility, or else...

Michael Zarlenga is my "hero of the week". After cooperating with the local zoning board for several months and spending a ton of money on plans and architectural reviews, the zoning board had a change of heart and sent him back to the drawing table. However, he didn't have the additional cash needed to go back to the drawing table, so instead of upgrading his shop, he was forced to shut it down and leased it out to a sex shop - right in the middle of the historic district.

Now the town is upset that instead of dry goods/hunting/fishing store, they have a sex shop in the historic district. Bet they wish that they had been flexible now!

Even worse, now a public attorney, Randolph Sengel, has decided he is going to take on the adult store and try to have the space darkened through some legal means. Not to belittle the power of the zoning board, but the moral high ground here would be to approach them about being a little more flexible. Randolph Sengel wins the dumb lawyer of the week award.

If it is not obvious, I too have had my run-ins with the empire building public servants on the zoning, and similar, boards. I've yet to win an argument, and unfortunately found it easier to work around them, rather than with them.

Saturday, February 28, 2009

Warren Buffet's Annual Letter

I'm admittedly a cautious fan of Mr. Buffet, and enjoy hearing his insights. His annual letter can be found on his website here, and numerous other folks have highlighted important parts of it, here, here, and here (some of it is even real estate related). He has numerous prescient comments ranging from derivatives, to underwriting mortgage loans, to the pitfalls of investing in the latest bubble - government debt.

So, I don't have much more to add, and instead will take the low road and just highlight the lines that made me think, "Really!?!" (in your best Seth Meyers voice)

As we view GEICO’s current opportunities, Tony and I feel like two hungry mosquitoes in a nudist camp. Juicy targets are everywhere...
Participants seeking to dodge troubles face the same problem as someone seeking to avoid venereal disease: It’s not just whom you sleep with, but also whom they are sleeping with...

And perhaps, my favorite is the link to the Clayton IHouse (which I think is a great idea, and hope it takes off more than all the competitors who are lagging in this markety), which opens with background music that is a cross between light-techno, heavy-sax-laden elevator music, and soft-porn-background-music.

Friday, February 27, 2009

Closures and Layoffs

Sears is closing its store at Eastland Mall in Charlotte NC. The fact that it took so long (just 3 weeks ago, ESL was stating publicly how committed he was to that location) is smear against the company. This mall has disintegrated into an unsafe place responsible for a high level of crime and has no anchors (Sear's was the last), but this disintegration started before the turn of the century and it was in bad shape back then. After losing money for some significant period of time and working with local groups to come up with plans to revive the site, the former owner, Glimcher, bowed out and turned in the keys in 2008.

The comments in the Charlotte Observer story are mildly amusing if you're bored. Commentators call each other racists (the mall is located in predominantly minority part of town) and blame everyone for the Mall's failure (except the owner and manager of the property).
Regardless, it got me looking for other closures, of which I try to keep a close eye on. The list is really growing. David Bodamer has a nice one compiled at the bottom of his article on Sear's closures. However, Mark Herschmeyer has the best weekly update on closures and layoffs at CoStar.com, and I haven't found one that rivals the depth and quality - but let me know if I'm missing a good one.

Rent Control Regulation Proposals

NY is proposing to make changes to rent regulations that would make it vastly more complicated to execute the deregulation strategies that are being undertaken by several private equity groups. The most notable includes the Tishman/Blackrock Peter Cooper Village/Stuyvesant Town (PCV/ST) and Stellar Management's Riverton, but the list doesn't end there.

Deal Junkie and Bloomberg did a fine job summarizing the changes. The largest new hurdle seems to be the increase in the destabilization threshhold from $2,000 to $2,700. Further, one year ago in March 2007, NY put into place legislation that made it demonstrably easier to sue your landlord if he repeatedly, and unsucessfully, attempted to deregulate your apartment based on false accusations.

Can't say that it is easy to feel sorry for the PE groups though. Some others include.

Savoy Park ($210mm, CSMC 2007-C1) sponsored by Vantage and Apollo
Meyberry House ($72.4mm, CSMC 2007-C4) sponsored by J.Goldberg and A.Cohen.
New York City Apt. Port. ($195mm, MSC 2007-IQ14) - sponsored by Insureprofit, which filed for bankrupcty last year.
Broadway Portfolio ($70mm, CSMC 2007-C2) - Vantage and Apollo
Esquire Portfolio ($31mm, CSMC 2007-C4) - Vantage and Apollo
Villas Parkmed ($300mm, CD 2006-CD2 - Stellar and Rockpoint are the same sponsors athat are involved in Riverton; This property is located in California, but is the same type of story.
The Axton ($21mm, MSC 2007-HQ12)

Friday, February 20, 2009

Riverton defaulting

Riverton's foreclosure is today. It seems that the mezz lender (CBRE) is going to take a turn at the helm to see if they can make it profitable after taking out the current equity holder (Stellar).

Reuters

Fitch

It's just the most obvious rent-control flip problem on the radar. There are several others I've written about previously. Jeff Bernstein details some of the new rent control laws in the pipeline that are going to further exacerbate the problem for PE landlords playing the deregulation game The game was mostly played in NYC, but also in San Francisco (The owner of Riverton actually has a similar project in SF) and other cities with rent-regulation.

Either way - you know you have problems when 96-year old women (see image from NYTimes to the right) are gathering in the streets protesting with signs disparaging Private Equity - I mean really...

Moody's completed downgrades


Following 7 days of correcting their ratings on 1,422 bonds worth over $50 billion, Moody's stated it was done with its review. The actions were highly anticipated for some time, and made for a volatile market the last two weeks.

Obviously, Moody's made a huge mistake - they are not downgrading these due to deterioration in quality, but rather due to changes in their model. And their new model is only calling for 5% losses on recently issued deals with the weakest credit profiles. Historical losses when times were good are 3%! I don't know how they are still in business.
Publish Post

Friday, February 6, 2009

PCV/ST Deals Downgraded

How prescient. Deal Junkie brought a lengthy article on PCV/ST to our attention this morning, and by this afternoon Moody's had started it's wave of mutilation in CMBS due to the same transaction. The Aaa-rated AJ class was downgraded to A2...

Frankly, I don't think it was unexpected and I figured it was mostly priced in, but it is putting surprising pressure on spreads.

Thursday, February 5, 2009

Run for the Hills!!!! AAA Downgrades are coming...


Not sure if that is Tad Philipp enjoying his new found freedom on the buy side, or Nick Levidy chasing a couple of the weaker AAA broads bonds through the valley as he thins the herd.

Moody's is going to whack AJs down half a dozen notches over the next couple of months according to a release to day.
the junior Aaa-rated classes, to be downgraded by four to five notches on average.

Expect losses of just 5% on average (seems low).
Moody's generally rated conduit and fusion transactions from 2006 through 2008 to an expected loss of about 2%, but now expects that deals from these vintages will experience losses of approximately 5% on average.

Credit problems on the horizon? Who'da'thunk...
"Early in the current economic crisis, our biggest concern was the impact of a liquidity crunch on commercial real estate," says Moody's Senior Vice President, Michael Gerdes. "However, Moody's now expects a significant overall decline in property cash flows as a result of a higher incidence of tenant defaults and bankruptcies and a sharp decline in lease renewal rates."

Lynx


Clueless CMBX Investor (but Clueless has still made a lot of money over the last year, maybe he's just playing dumb.)

CRE TBI cliff diving

CRE and Resi are so different in so many ways, I don't understand why folks try to draw corollaries.... The whole article should be trashed based on the headline alone, but the conclusion is wrong too.

Some other Resi folks who aren't quite in tune with the CRE market, but do manage to speak with great confidence and authority:

From Christmas, CR informs the world that he knows nothing about CRE when he is caught off guard that all properties are put into special purpose entities and loans are non-recourse...

I hate to be speculative without seeing the actual Cushman & Wakefield report quoted in the NYTimes, but I'm guessing we're talking about two different locations when comparing the cost of retail space in Manhattan. Obviously, retail space that is leasing for over $2k per square foot (i.e. 666 Fifth Avenue to Abercrombie and Diesel's space at 685 Fifth) should sale for more than $3k per square foot.

Till mixing? I appreciate this guy's writing style, but he lost me a few times with the analogies. You are absolutely not supposed to mix the tills if you have multiple properties with different SPEs for each. People do. Michael B Smuck did, once a couple of decades ago, and again in 2007, and as the resi author indicates, he failed miserably.

CRE loans do not default because property values decline, unless they mature and cannot get refinanced. Hardly any CMBS loans mature until after 2010. Your property value could go to $0, and if you are still bringing in more rent than your expenses, you continue to operate.